Average Deal Size: What the Published Figures Assume
The formula is simple and the two definitional choices inside it decide the answer. What one dated survey actually publishes, and the cuts that make it usable.
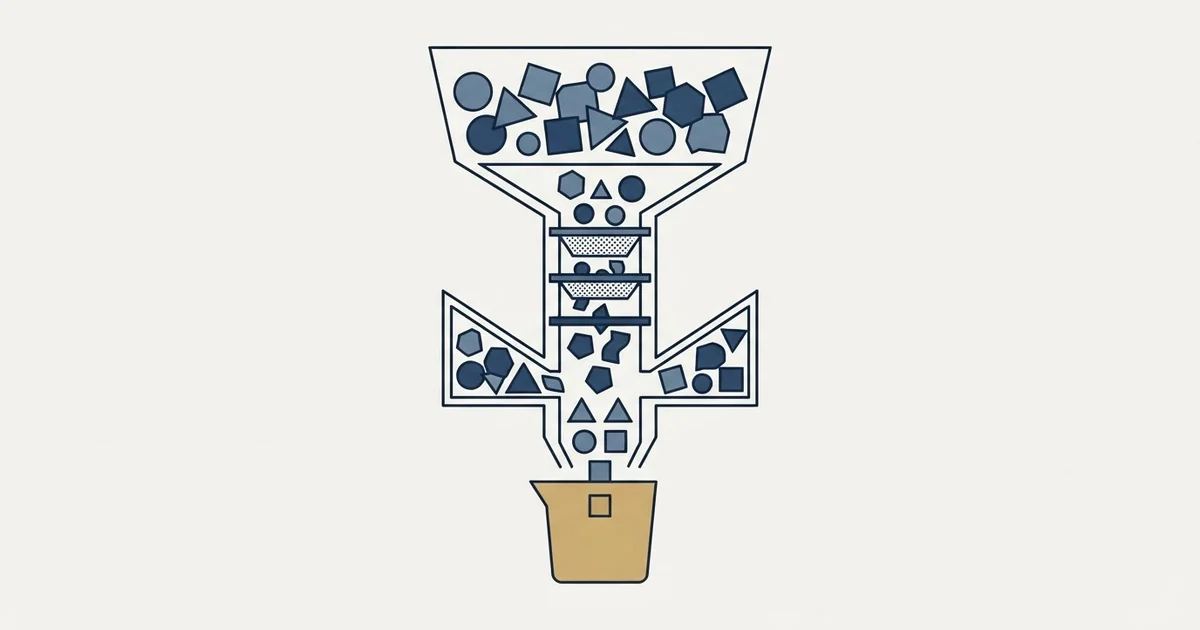
Average deal size means the average value of the deals a team wins: total closed-won revenue divided by the number of closed-won deals, so $500,000 across 50 deals is $10,000. Two choices decide the result, which revenue counts and which deals count, and SaaS Capital's 2026 survey puts the private SaaS median ACV at $24,266.
Key takeaways
- The formula is total revenue from closed-won deals divided by the number of those deals, the calculation Salesforce's blog publishes.
- In the illustrative quarter here, the same six deals average $50,000, $25,000 or $18,333 depending on the numerator and on whether expansions count.
- SaaS Capital's 2026 survey of over 1,000 private B2B SaaS companies reports a median ACV of $24,266, down from $26,265 the previous year.
- The survey's cuts move the median further than its headline moves: $18,643 bootstrapped against $39,880 equity-backed, and $26,269 against $61,802 by retention.
Reviewed and updated September 19, 2026
A board deck arrives with one line reading "average deal size" and a figure beside it, and no other context. Nobody in the room can say whether that number came from closed-won revenue divided by closed-won deals, from booked contract value divided by every opportunity that reached the pipeline, or from a first-year figure on multi-year contracts. Three defensible calculations produce three different numbers from the same quarter, and the deck shows one of them.
Average deal size looks like the least ambiguous metric on a revenue dashboard and is one of the easiest to compute two ways by accident. The published benchmarks make that worse rather than better, because a figure quoted without its population is a number about somebody else's company.
This page sets out the formula, the figures that are actually published with a dated source and a stated sample, and the segmentation that has to travel with any of them before they mean anything.
What does average deal size mean?
Average deal size, also called average deal value, is the average value of the deals a team wins in a period: total revenue from closed-won deals divided by the number of those deals. Salesforce's blog works it through as $500,000 across 50 closed deals, an average of $10,000. In sales it is a planning unit more than a score, because it sets what each sale can afford to cost.
The same number turns up as a form field and an interview question, usually as a request for your average deal size in USD, in thousands. The asker wants one figure in thousands, so an illustrative $25,000 average annual contract is answered as 25. Add the definition in a few words, such as annual value on new business closed-won, because the two choices below can double the figure without anything about the selling changing.
The formula, and the two choices inside it
Salesforce's own blog post on the metric, published on 26 April 2024 under the byline Samuel Holzman, gives the calculation plainly. It states the formula as "Average deal size = Total revenue generated / Total number of closed-won deals" and works it through with an example: a company generating $500,000 in revenue across 50 closed deals has an average order size of $10,000.
Two decisions sit inside that arithmetic and neither is visible in the result.
The first is what goes in the numerator. Total contract value, first-year value, annual recurring value and recognised revenue all produce different averages on the same set of deals, and the gap widens with contract length. A three-year contract counted at total value makes the average roughly triple what an annualised count produces.
A worked example, illustrative only, shows how far apart the choices land. Take a quarter with four new-business deals: one-year contracts worth $20,000 and $30,000, and two three-year contracts worth $25,000 a year each, plus two expansion deals worth $5,000 a year each. In that illustrative quarter the average is $50,000 on total contract value across the four new deals, $25,000 on annual contract value across the same four, and $18,333 on annual value once the two expansions are counted in. Same quarter, same deals, three answers.
The second is what qualifies for the denominator. Closed-won deals is the common choice and the one Salesforce's formula names. Teams that include renewals, expansions or downgrades in the same count are measuring something else, usually something flatter, because expansion deals cluster smaller than new business. The same page recommends reading the metric beside win rate, sales cycle length and customer lifetime value rather than alone, which is the honest instruction and the one that gets skipped.
That denominator problem is the same one win rate and closing ratio each carry, and it is worth settling once for all three rather than three times separately.
Annual contract value is the unit worth standardising on if any external comparison is coming, because it is the unit the published surveys use.
What is actually published, with a source and a sample
Very little of what circulates as an average deal size benchmark names its population. One recurring exception is worth reading in full.
SaaS Capital publishes an annual survey of private B2B SaaS companies. Its post "What is the Average Deal Size for Private SaaS Companies?", published on 14 August 2026, describes the source as its 15th annual report with data from over 1,000 respondents, and gives its headline figure: across all companies in the 2026 survey, the median annual contract value is $24,266, down from $26,265 the previous year. The post is explicit about why it exists, stating that public company metrics "tend to skew higher due to scale, funding, and market position" and that the survey is focused solely on private, B2B SaaS companies.
Three cuts of that same survey do more work than the headline.
By company size, the same post reports that companies with $10 to $20 million in annual recurring revenue reported a median annual contract value of $46,788, which it puts at 85% higher than the median of $25,278 reported by companies with $3 to $5 million in ARR. The same SaaS Capital post states that the pattern of rising deal size with company size begins to break down above $20 million in ARR.
By retention, the same post publishes a median annual contract value of $61,802 for companies reporting net revenue retention of at least 120%, against $26,269 for companies reporting NRR below 120%.
By funding type, for private companies above $1 million in ARR in 2025, the post reports bootstrapped companies at a median ACV of $18,643 on a median ARR of $4,400,000, and equity-backed companies at a median ACV of $39,880 on a median ARR of $9,600,000.
Its own closing position is the one to carry away: the post states there is no universal benchmark for deal size that applies to every SaaS company, and offers the data as a solid reference point for comparing ACVs against peers.
The same figures, as that publisher reports them, with the population attached to each:
| Population, as SaaS Capital publishes it | Median ACV |
|---|---|
| All respondents, 2026 survey | $24,266 |
| All respondents, previous year | $26,265 |
| Companies at $3 to $5m ARR | $25,278 |
| Companies at $10 to $20m ARR | $46,788 |
| NRR at or above 120% | $61,802 |
| NRR below 120% | $26,269 |
| Bootstrapped, above $1m ARR | $18,643 |
| Equity-backed, above $1m ARR | $39,880 |
Read as pairs, SaaS Capital's cuts move the median far more than the headline moves between years: the headline fell from $26,265 to $24,266, while the size cut runs from $25,278 to $46,788, the retention cut from $26,269 to $61,802 and the funding cut from $18,643 to $39,880. SaaS Capital's post adds that ACVs decreased from the previous year for companies with $1 million to $20 million in ARR.
Those figures belong to that survey and that population. A services business, an on-premise vendor or a company selling to consumers sits outside it, and nothing in the numbers themselves marks the boundary once they are pasted into a deck.
Why a blended average is the least useful cut

An average across a book with two segments in it describes neither segment.
A company selling a self-serve tier at low value and an enterprise tier at high value has a blended average sitting between the two, at a value no customer has ever paid. Watching that blended number move tells you the mix changed. It does not tell you whether either segment got better or worse, and those are the two questions a sales leader is actually asking.
The fix is not sophisticated. Cut the average by the axes that genuinely change the number, and read each cut on its own: segment, product line, new business against expansion, and channel. Where a cut has too few deals to be stable, say so and read it as a range rather than as a point. Deal counts inside a quarter are usually small enough that one unusual contract moves the mean noticeably, which is why a median beside the mean is worth carrying.
The same reasoning appears in the surveys themselves, which report medians rather than means for exactly this reason.
Written out, a figure that can travel carries its definition with it: the numerator, the deals counted, mean or median with the deal count, and the cut, plus the publisher, date and population surveyed when it comes from outside.
Average deal size, this quarter
$25,000 1
Numerator: annual contract value 2
Deals counted: new business closed-won, expansions excluded 3
Mean $25,000, median $25,000, on 4 deals 4
Cut: one segment, one product line 5
- 1The number a deck usually shows on its own.
- 2Which numerator: total contract value, annual value or recognised revenue.
- 3Which deals count: new business only, or renewals and expansions too.
- 4Mean or median, and how many deals it rests on. Four deals is too few to read as a point.
- 5The cut, and for an external benchmark the publisher, the date and the population surveyed.
What the number actually decides
Deal size is a design input rather than a scoreboard, and it decides more downstream than a dashboard line suggests.
It decides how much acquisition effort a deal can carry. A motion whose average deal is worth a few thousand dollars a year cannot support a long multi-threaded enterprise process, and one worth six figures cannot be served by a purely self-serve funnel. That constraint is the whole content of transactional selling, and it is arithmetic rather than philosophy.
It decides the shape of the commission plan. The rate people argue about is downstream of contract value and margin, which is why a commission plan that survives a bad quarter derives the rate from deal economics rather than from a published average.
It decides which outbound motion is affordable at all. The threshold that matters is the contract value at which a sale can support human selling time, and B2B SaaS lead generation on either side of that threshold works through what changes on each side of it.
And it decides what a pipeline coverage number means. Coverage is a multiple of a target, and a target built on an average that is drifting produces a coverage figure that looks stable while the underlying book changes shape.
Where it belongs on a dashboard
Average deal size is a lagging figure with a long tail, and reading it weekly produces noise and a standing invitation to explain variance that is not there. A quarterly read, cut by segment, against the same cuts from the previous four quarters, is what makes a trend visible.
It also belongs beside a leading figure rather than alone. Which numbers change a decision sets out the workable set and the pairing rule: every lagging number carries a companion that says whether the change came from selling or from mix.
For an outbound team the practical consequence is narrow. If the average is falling and the segment mix has not changed, the targeting has drifted down-market, and the fix sits in the list rather than in the copy. If the average is falling because the mix changed, that was a decision somebody made, and the metric is reporting it correctly.
Where the constraint turns out to be the number of qualified conversations at the top rather than the size of the ones that close, no amount of deal-size analysis repairs it. We are paid on attended meetings that meet criteria agreed in writing before launch. See what a first campaign produces before rebuilding a forecast around a metric that may not be the binding one.
The short version

The formula is total revenue divided by closed-won deals, and the two definitional choices inside it decide the answer more than the selling does. Published benchmarks are usable only with their publisher, their date and their surveyed population attached, and the one survey worth quoting here says plainly that no universal benchmark exists.
Cut the number before averaging it, carry a median beside the mean when deal counts are small, and read it beside win rate and cycle length rather than on its own. Then use it for what it is good for, which is deciding what a sale can afford to cost.
Figures are quoted as each publisher states them on its own page. Verify current figures with the publisher before relying on them.
Sources: SaaS Capital, What is the Average Deal Size for Private SaaS Companies?, Salesforce, Average Deal Size: The Secret to Forecasting with Confidence
Frequently asked questions.
Frequently asked questions- What does average deal size mean?
- It is the average value of the deals a team wins in a period, also called average deal value. Divide total revenue from closed-won deals by the number of those deals: Salesforce's blog uses $500,000 across 50 deals, which gives $10,000. It matters in planning because it sets how much selling effort each deal can afford.
- How do I answer 'what is your average deal size in USD (in thousands)'?
- Give one number in thousands of dollars, so a $25,000 average annual contract is answered as 25. Then state the definition in a few words, usually annual contract value on new business closed-won, because counting total contract value or including expansions can move the figure a long way without the selling changing at all.
- How do you calculate average deal size?
- Divide total revenue by the number of closed-won deals in the period, the formula Salesforce's own blog publishes. Before running it, decide which revenue figure goes in the numerator and whether renewals and expansions count in the denominator. Both choices change the answer, and neither is visible in the result once it is computed.
- What is a good average deal size?
- There is no general answer, and the one dated survey quoted here says so directly: SaaS Capital states there is no universal benchmark for deal size. Its own cuts show why, with medians from $18,643 to $61,802 depending on funding and retention. The useful comparison is against your own previous quarters on the same definition.
About the author.

B2B cold email experts helping companies generate qualified leads through done-for-you outreach campaigns.
RevenueFlow Team
Explore more.
Ready to scale your outreach?
We build GTM engines that book real meetings. See the receipts.
Related articles.
SDR Outsourcing for Financial Services: The Third Party
What a bank, broker-dealer, adviser or agency's regulators say about an outside team that speaks for it, the licensed line, and which arrangement survives due diligence.
SDR Outsourcing for Business Brokers: The Fee Timing
Whether a success-fee brokerage should rent sales development at all: the fee timing, the texts that limit what an outside person may say about value, and who signs.
Appointment Setting for Business Brokers: The Seller Meeting
What a bought meeting with a business owner has to be for a brokerage: the three-part qualification, the confidentiality rules, the licence line and the owner's reasons.
Win Rate Benchmarks: Which Figures State a Population
A catalogue of the published average sales win rates, sorted by whether the page names the population behind its own number. Most do not.
B2B Lead Lists for Aviation Companies: Build or Buy
Aviation is one of the few industries whose accounts are published by its regulator, which changes what is worth buying and what is worth downloading yourself.
LinkedIn Outreach for Banks: A Regulated Message
How a bank's relationship managers use LinkedIn to reach business owners: what the FFIEC guidance, FINRA's notices and LinkedIn's own rules require, and where to stop.